Executive boardroom with financial dashboards overlooking the Phoenix, Arizona skyline at dusk

ADHS-licensed Arizona cannabis operators only

Arizona Cannabis CPA | Cannabis Accounting, Tax & 280E Compliance Services

Speak directly with an Arizona cannabis accounting specialist.

We are an Arizona cannabis CPA firm working exclusively with marijuana establishments licensed by the Arizona Department of Health Services — no general business clients. Licensed operators here do not have a normal accounting problem: IRC Section 280E disallows ordinary deductions, inventory accounting decides the tax outcome, dispensary reporting has to reconcile point-of-sale data to seed-to-sale movement, and every position has to be documented well enough to survive examination.

Specialized cannabis accounting, bookkeeping, tax and CFO services for Arizona dispensaries, cultivators, manufacturers and licensed cannabis operators. That means inventory-grade cannabis accounting and monthly close, 280E and cost of goods sold strategy, Arizona transaction privilege tax and 16% adult-use excise filings, fractional CFO advisory and IRS or ADOR audit defense.

Practice focus
Cannabis only — no general business clients
Coverage
Every Arizona license type, Phoenix to Tucson
Method
Inventory-first accounting, documented positions

What is cannabis accounting?

Cannabis accounting is specialized financial accounting for licensed cannabis businesses. It covers bookkeeping, inventory and cost accounting, financial reporting, tax compliance, cash controls, point-of-sale reconciliation and seed-to-sale reconciliation in one system of record. For Arizona operators it has to satisfy IRC Section 280E federally while meeting ADHS recordkeeping expectations and Arizona transaction privilege tax and adult-use excise reporting at the state level.

2026 Advisory

Schedule III Planning for Dual-Licensed Arizona Operators

Federal rescheduling of cannabis to Schedule III would switch off the IRC Section 280E deduction disallowance that currently drives Arizona effective tax rates far above statutory rates. We are modelling expense apportionment, entity structures and amended-return posture now, so dual-licensed Arizona establishments can move on day one rather than spend a filing season rebuilding their books.

Review Our 280E Restructuring Frameworks

Regulatory & accounting frameworks

Documented compliance architecture for Arizona establishments

ADHS Licensing & Proposition 207 Compliance

Our workpapers tie operating results back to the Arizona Department of Health Services rules that govern marijuana establishments, dual-licensed dispensaries and testing facilities under Proposition 207 and the Arizona Medical Marijuana Act — so medical and adult-use activity stays separable in the ledger and defensible on examination.

Systems, Banking & Payments Architecture

We select and implement the accounting, point-of-sale and seed-to-sale stack an Arizona operator can actually reconcile, then help open and maintain cannabis-friendly banking, cash logistics and compliant payment rails for independent Phoenix, Tucson and Flagstaff businesses.

Advanced IRC Section 280E & Cost Accounting Framework

Between Section 280E, Arizona transaction privilege tax and the 16% adult-use excise tax, plant-touching margin disappears quickly. We build inventory-grade cost accounting that isolates capitalizable production cost from disallowed selling and administrative spend, with the substantiation an examiner expects.

Core practice areas

Where cannabis operators lose money — and where we work

Each practice area below has a dedicated page covering the methodology, the documentation standard and the questions Arizona operators ask most.

Cannabis accountants reviewing financial reports and margin analytics on screen in a dark executive office
Margin, inventory and tax exposure reviewed together — the way a cannabis engagement actually runs.

Cannabis accounting

Cannabis Accounting Services for Arizona Businesses

Cannabis accounting is not general-ledger work with a different logo on the invoice. A licensed Arizona operator carries an inventory-driven federal tax position, a seed-to-sale system of record that must agree with the books, and a state transaction tax regime that runs on its own calendar. Our cannabis accounting services are built around those three constraints from the first journal entry.

Every engagement starts with a chart of accounts that separates inventoriable production cost from disallowed selling and administrative spend, because that structure is what decides the tax outcome twelve months later. From there we run the monthly cycle: bank and merchant reconciliations, inventory roll-forwards tied to Metrc quantities, accrual entries, and cannabis financial reporting a lender, investor or examiner can actually follow.

The recurring monthly work is concrete: bookkeeping and coding, accounts payable, bank, merchant and cash reconciliation, point-of-sale reconciliation to the ledger, inventory accounting and seed-to-sale reconciliation, cost of goods sold review, payroll allocation between inventoriable and disallowed activity, accrual of Arizona transaction privilege tax and the applicable cannabis excise tax, and a reviewed close that produces financial statements.

Around that cycle sit the controls and the record: segregation of duties in a cash-intensive environment, documented approval for inventory adjustments and waste, and the workpapers that make the 280E position and the state filings examinable. Audit readiness is not a separate project here — it is what a correctly run close leaves behind.

A traditional CPA can close a set of books. A cannabis accountant has to close them in a way that survives IRC Section 280E, ADHS recordkeeping expectations and an ADOR review at the same time.
  • Monthly accounting and close

    Full-cycle close with documented review, delivered on a fixed calendar.

  • Chart of accounts setup

    Built to isolate 471/263A inventoriable cost from 280E-disallowed spend.

  • Inventory accounting

    Perpetual inventory valued and reconciled to seed-to-sale quantities.

  • Reconciliations

    Bank, merchant, cash, intercompany and inventory reconciled every period.

  • Financial reporting

    GAAP-oriented statements plus unit economics by license and location.

  • Cannabis accounting systems

    Ledger, POS and seed-to-sale stack selected and implemented to tie out.

Dispensary operations

Arizona Dispensary Accounting & Cannabis Bookkeeping Services

Arizona dispensary operators lose more margin to unreconciled retail data than to almost anything else. Point-of-sale totals, Metrc movement, merchant deposits and the drawer count rarely agree on their own, and a month that closes without tying them out leaves the operator guessing at both gross margin and excise exposure. Our dispensary accounting and cannabis bookkeeping work exists to remove that guesswork.

We reconcile daily sales to deposits, reconcile inventory to seed-to-sale, control cash across shifts and vaults, and close each month on a fixed schedule so the financial statements arrive while they are still useful for pricing and purchasing decisions.

  • POS reconciliation

    Register, Metrc and ledger reconciled line by line, with variances investigated.

  • Sales reconciliation

    Daily sales tied to merchant settlements, delivery receipts and deposits.

  • Cash management

    Shift counts, vault logs, armored pickups and segregation-of-duties controls.

  • Inventory tracking

    Perpetual counts, cycle counts, shrink analysis and inventory valuation.

  • Monthly close

    Accruals, excise and TPT liabilities, and a reviewed close package each period.

  • Financial statements

    Store-level P&L, balance sheet and cash flow with comparative trending.

Tax & compliance

Arizona Cannabis Tax Accountant Services & 280E Compliance

Cannabis tax is a specialty because the ordinary rules are switched off. Under IRC Section 280E, a plant-touching business cannot deduct ordinary and necessary expenses, so the entire lawful path to a defensible federal position runs through cost of goods sold and the inventory rules of Sections 471 and 263A. A cannabis tax accountant who does not build the inventory model first is not reducing tax; they are just filing.

We set the costing methodology, document it in writing, tie it to the general ledger, and maintain the workpapers behind every allocation so the position holds on examination. Alongside that, Arizona transaction privilege tax and the 16% adult-use excise tax are filed on their own ADOR calendar and reconciled to the same sales data the federal return relies on. See our full 280E tax compliance methodology.

  • IRC Section 280E strategy

    Reseller versus producer positioning, entity review and expense apportionment.

  • Cost of goods sold

    471/263A capitalization models reconciled to production and seed-to-sale output.

  • Tax planning

    Quarterly effective-rate modeling, estimated payments and cash tax forecasting.

  • Documentation

    Methodology memoranda, labor studies and a standing audit file kept current.

Advisory

Cannabis CFO & Financial Advisory Services in Arizona

Most Arizona operators do not need a full-time finance chief; they need someone who can price product, defend a margin and answer a lender's questions with numbers that hold. Our cannabis CFO services put a fractional CFO on the business at the cadence it actually requires — monthly for a single dispensary, weekly through a build-out or capital raise.

  • Forecasting

    Driver-based models built on real throughput, pricing and 280E-adjusted tax.

  • Budgeting

    Annual operating budgets with variance reporting against the monthly close.

  • Cash flow analysis

    Thirteen-week cash forecasting for a cash-intensive, tax-heavy operation.

  • Profitability analysis

    Margin by category, SKU, location and license to guide purchasing.

  • Expansion planning

    Site, license and capacity modeling before capital is committed.

  • Investor & lender reporting

    Diligence-ready reporting packages and capital-readiness review.

License types

Cannabis Businesses We Serve Across Arizona

Dispensaries

Dispensary accounting and cannabis retail reporting for ADHS-licensed and dual-licensed storefronts: POS-to-ledger reconciliation, medical versus adult-use separation, excise and TPT liabilities, and store-level profitability reporting.

Dispensaries accounting

Cultivators

Cultivation accounting built on production costing: direct materials, cultivation labor, grow-room utilities and depreciation capitalized into inventory, with harvest-batch costs and inventory tracking reconciled to seed-to-sale quantities.

Cultivators accounting

Manufacturers

Cannabis manufacturing accounting for infused-product and extraction operations: bill-of-materials costing, yield and conversion analysis, work-in-process valuation and per-unit cost analysis by SKU.

Manufacturers accounting

Distributors

Cannabis distributor accounting covering transfer manifests, freight and logistics cost, consignment and wholesale terms, receivables management and margin reporting across brand relationships.

Distributors accounting

By license type

Cannabis Accounting for Arizona Dispensaries, Cultivators, and Manufacturers

Dispensaries

POS reconciliation to deposits and seed-to-sale, cash controls across shifts and vault, retail inventory valuation, transaction privilege tax and adult-use excise accruals, category margin reporting and monthly bookkeeping. See dispensary accounting.

Cultivators

Production costing by harvest batch, cultivation labor allocation supported by a documented basis, inventory roll-forwards tied to plant tags, cost of goods sold capitalization and cultivation financial reporting. See cultivation accounting.

Manufacturers & processors

Raw material tracking, work-in-process and finished-goods valuation, production labor and overhead absorption, yield and conversion analysis, and per-unit inventory costing by SKU. See cannabis manufacturing accounting.

Choosing a provider

Why Arizona Cannabis Businesses Need a Specialized Cannabis Accounting Firm

Most accounting firms are built for businesses whose expenses are deductible and whose inventory is a routine subledger. Neither assumption holds for a plant-touching Arizona operator. Under IRC Section 280E the federal return is decided by what was capitalized into inventory during the year, which means the tax outcome is set by bookkeeping decisions made months before anyone opens a return. A firm that has not done that work before tends to discover the problem at filing season, when it can no longer be fixed.

The second difference is reconciliation. A licensed operator runs three systems that must agree — point-of-sale, the state seed-to-sale record and the general ledger — plus cash and merchant settlements that rarely tie out on their own. Reconciling those sources is ordinary practice in a specialized cannabis accounting firm and unfamiliar territory almost everywhere else.

The third is documentation. Arizona layers transaction privilege tax and the adult-use excise tax on top of the federal position, and both are examined against the same sales data. Cannabis accountants who work in this industry maintain a standing audit file — costing memoranda, labor allocation support, inventory workpapers — because they expect the question rather than react to it. That is the practical reason operators evaluating accounting firms should weight industry experience over general credentials.

What to Look for in a Cannabis Accounting Firm

  • Cannabis-industry accounting experience, not a general practice with one cannabis client
  • Working knowledge of IRC Section 280E and cost of goods sold under Sections 471 and 263A
  • Arizona tax knowledge: transaction privilege tax, adult-use excise tax and city-level components
  • Inventory accounting capability, including perpetual valuation and roll-forwards
  • Seed-to-sale reconciliation experience with the operator's tracking system
  • Familiarity with dispensary, cultivation and manufacturing cost structures
  • A documented monthly close process on a published calendar
  • Audit-ready workpapers maintained during the year, not rebuilt after a notice
  • Management reporting an owner, lender or investor can actually use

How it differs

Cannabis Accounting vs. General Business Accounting

AreaGeneral business accountingCannabis accounting
DeductionsOrdinary and necessary business expenses are generally deductibleIRC Section 280E limits federal deductions for plant-touching operators
InventoryStandard inventory accountingDetailed inventory and COGS documentation plus seed-to-sale reconciliation
Banking and cashTraditional banking environmentCash-intensive controls, vault logs and deposit verification
Transaction taxesStandard sales-tax workflowArizona transaction privilege tax plus cannabis-specific excise considerations
Chart of accountsGeneric chart of accountsCannabis-specific segmentation of inventoriable and disallowed cost
ReconciliationBank and inventory reconciliationPOS, inventory, cash and regulatory-system reconciliation together

General description only. Tax treatment depends on facts, license type and entity structure.

Capabilities

Cannabis Accounting Disciplines This Practice Covers

  • Cannabis accounting

    Full-cycle accounting for licensed operators, from chart of accounts design through a reviewed monthly close.

  • Cannabis bookkeeping

    Transaction-level bookkeeping with daily reconciliation discipline rather than a quarterly catch-up.

  • Dispensary accounting

    Retail-specific accounting covering POS, cash, deposits, inventory and store-level margin reporting.

  • 280E tax planning

    Cost segregation and documentation built during the year so the federal position is supportable.

  • Inventory accounting

    Perpetual inventory valuation, cycle counts, shrink analysis and roll-forwards tied to the ledger.

  • Seed-to-sale reconciliation

    Tracking-system quantities reconciled to the inventory subledger and POS depletion at SKU level.

  • Arizona TPT & excise tax

    Transaction privilege tax and adult-use excise accrued as sales post, filed on the ADOR calendar.

  • Fractional CFO

    Forecasting, budgeting, cash planning and lender-ready reporting at the cadence the business needs.

  • Internal controls

    Segregation of duties, cash handling procedures and review controls appropriate to a cash-intensive operation.

  • Audit & examination support

    A standing audit file and representation if the IRS or the Arizona Department of Revenue examines a filing.

Decision guide

How to Choose a Cannabis Accountant or Accounting Firm in Arizona

Start with specialization. Ask how much of the practice is cannabis, which license types it works with, and whether it has built a 280E costing methodology from scratch rather than inherited one. Then ask about Arizona specifically: transaction privilege tax handling, adult-use excise reporting, and how medical and adult-use activity stay separable in the ledger.

After that, the questions are operational. What accounting and bookkeeping systems does the firm work in, and will it reconcile point-of-sale, cash and seed-to-sale data or expect the operator to hand over reconciled figures? How is inventory valued, and how often? What does the monthly close calendar look like, and what arrives at the end of it? How quickly does the firm respond during a filing week or an examination, and who is the actual point of contact?

Finally, ask to see the documentation standard: a costing memorandum, a labor allocation basis, an inventory workpaper. A firm that can show that structure is one whose numbers will hold up. Our Arizona cannabis accounting guide sets out the same standard we hold ourselves to.

Technical depth

The subject matter this practice is built on

Cannabis accounting is inventory accounting under a punitive federal tax regime, layered on seed-to-sale tracking, Arizona transaction privilege tax and a cash-intensive operating environment. These are the areas that decide whether an operator keeps margin.

Visit the resource center
  • IRC Section 280E
  • Seed-to-sale and METRC data
  • Cost of goods sold
  • Inventory accounting
  • 16% adult-use excise tax
  • Transaction privilege tax
  • Financial reporting
  • Cannabis payroll
  • Entity selection
  • IRS and ADOR audits
  • Cash-intensive businesses
  • Internal controls
  • ADHS compliance
  • Financial forecasting
  • Cannabis banking challenges

Industries served

Every Arizona license type has a different accounting problem

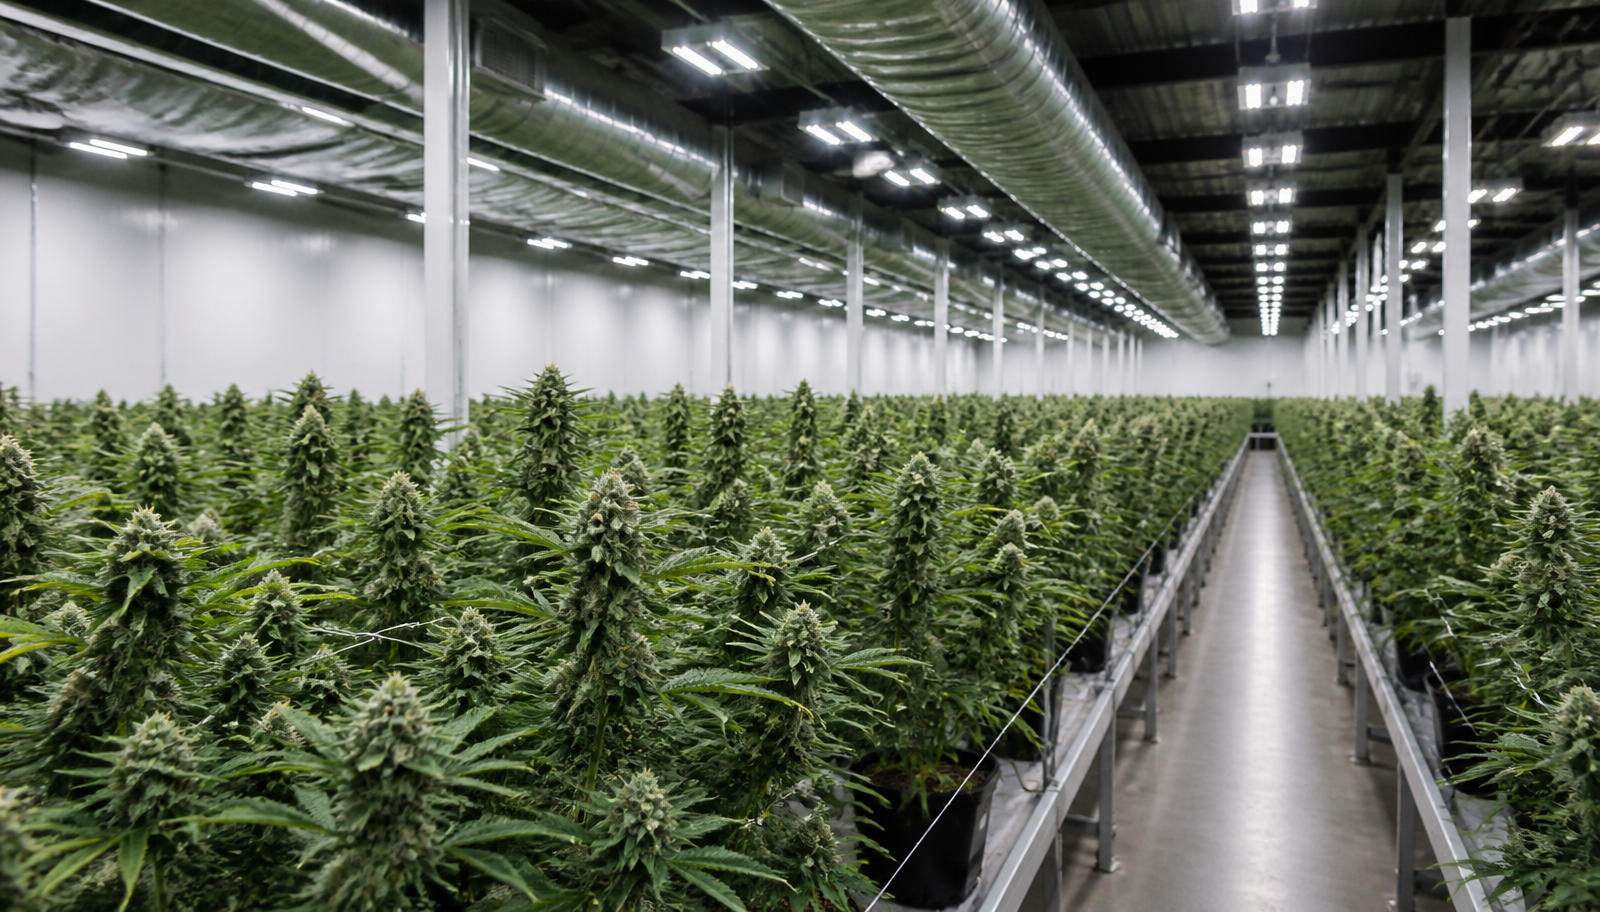
Licensed Arizona cannabis cultivation facility with rows of plants under commercial grow lighting
Cultivation, retail, manufacturing and distribution each carry a distinct inventory and 280E profile.

Full service list

Accounting, tax and advisory for licensed operators

Resource center

Educational guides for Arizona cannabis finance

Bound accounting and tax reference volumes beside a printed financial report on a dark desk

Questions

Cannabis accounting questions Arizona operators ask

Statewide coverage

Arizona market centers we serve

We work remotely with licensed operators statewide rather than from branch offices. Cannabis accounting, dispensary bookkeeping, 280E tax work and fractional CFO advisory are delivered across Arizona's licensed markets — Phoenix, Tucson, Scottsdale, Mesa, Tempe and Chandler through the Maricopa and Pima County corridors, plus establishments north and south of the valley.

Explore the practice

Where to go next

Consultation

Speak with an Arizona cannabis CPA

Bring your ADHS license types, current books and open TPT or excise filings. We will tell you what needs to happen first and in what order.